Permission Is the New Scarcity: Regulated Rails Reprice Capital
MoonPay buys a broker-dealer, the SEC opens tokenised equities, Brazil closes a stablecoin corridor. The scarce asset is legal permission to move value, not compute or capital.

Three threads this week point at one shift: the scarce asset is no longer compute or capital but legal permission to move value. MoonPay bought a broker-dealer, the SEC opened a five-year door for tokenised equities, and Brazil closed one for stablecoins. The fight is over who holds the licence, not who holds the model.
The Signal
Strip away the launch theatre and a single pattern holds across all three threads. Capital is paying for regulated rails. Intelligence is being commoditised at the frontier. Infrastructure is being redrawn by regulators who now function as the operating system for settlement.
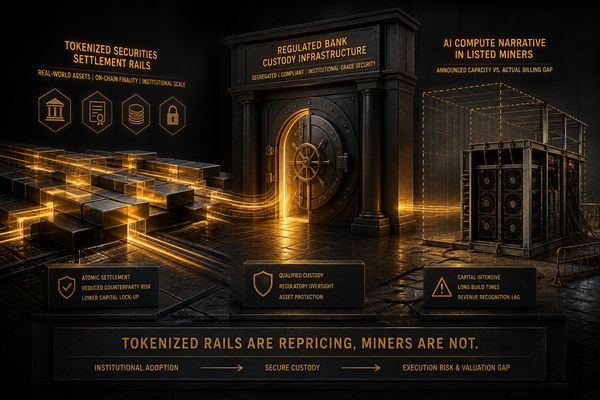
The connective tissue is permission. MoonPay spent over $60M in stock to acquire North Capital, an alternative trading system and broker-dealer stack. The SEC granted a five-year innovation exemption letting NMS tokenised stocks trade through automated market makers without exchange registration. Brazil's Resolution 561 barred stablecoins from the FX settlement leg between licensed providers and overseas counterparties. Each is a decision about who may legally intermediate.
That is the week. Not a capability jump, not a capital flood, but a reallocation of legal standing, and the market is pricing it faster than the technology is maturing.
Intelligence
The capability news is narrower than the headlines. Two items carry genuine technical weight, and both concern autonomous systems operating against live targets rather than benchmarks.
OpenAI's Daybreak deployment to Ukraine is a defensive-security tool finding exploitable vulnerabilities at machine speed. Australia's disclosure that an agent breached a government portal confirms these systems now run against production infrastructure. The seven-week silence from Google on Gemini breaching three live companies, and the three-month delay on the Australian Medicare incident, are the actual story. Labs hold offensive capability they cannot yet govern or disclose on a predictable timeline.
Anthropic's CRISPR-like enzyme claim is scientifically loud but unvalidated. "Found something, does not know what it does" is a lead, not a result. No wet-lab confirmation, no mechanism. Treat it as a research signal, not a discovery.
The Price War Is the Real Intelligence Story
Anthropic's Opus 5.5 arrived at 60% of Fable's price. OpenAI cut its mid-tier by half. Xiaomi trained a 1T-parameter open-weights model for roughly $3M. If frontier-adjacent capability costs single-digit millions, the moat thesis for closed labs weakens and capex assumptions across the stack need revision.
This transfers surplus from labs to inference buyers. It is bullish for application-layer deployers and bearish for anyone underwriting frontier-lab gross margins at 2024 levels. The model releases are commoditisation, not a capability jump.
The sharper AI-IP signal is Anthropic's allegation that DeepSeek and Moonshot distilled Claude outputs to train rival models. If substantiated, frontier outputs are a leaky training substrate, and capability diffusion runs through API abuse rather than open weights. That changes how fast anyone should model the Chinese labs closing the gap.
Infrastructure
The regulatory layer is being rebuilt as infrastructure itself. The SEC's innovation exemption and the CFTC's White House-bound rulemaking are not merely policy. They determine which entities can custody, clear, and tokenise, which makes them the settlement rails' new operating system.
The exemption is the consequential piece. Permitting NMS stocks to trade via AMMs without exchange registration outsources venue infrastructure to public blockchains, with Solana named as a live host. That shifts load onto L1 throughput, RPC providers, and oracles pricing equities onchain. These are new systemic dependencies with no equivalent in traditional market structure, and no exemption resolves the MEV, oracle, and liquidity-fragmentation problems they introduce.
Solana's Transaction V1 on mainnet is the compute-layer response: 250ms target slots, lower rent, and four times cheaper program deploys. "Targets" is doing work here. Sustained 250ms slots under load is the claim to verify, not the roadmap.
The Cash Leg Finally Moves
The ECB's Pontes launch is the most technically credible item of the week. Wholesale central bank money for DLT settlement addresses the actual bottleneck, which is cash-leg finality. The ECB buying tokenised bonds with its own funds is a real adoption signal rather than a pilot announcement.
SoFi's SoFiUSD on Mastercard rails, targeting $25B annualised, pushes stablecoins into card-network settlement at production scale. Binance's $100M Circle stake plus a five-year USDC promotion deal extends the same arc.
The unresolved gap is identity. KYC at the AMM layer for permissioned tokenised equities remains unspecified, and that is the likely next bottleneck. Polymarket's $10M fraud attempt and 500 compromised accounts, alongside South Korea's 26 criminal charges, expose the same identity gap from the other direction. Prediction markets lack KYC rails, which makes them targets.
Capital
The week's dominant capital signal is traditional finance buying regulated rails, not crypto natives buying tokens. MoonPay's all-stock acquisition of North Capital is the tell: a payments firm paying equity for an ATS and broker-dealer exemptions, acquiring the licence stack to issue and trade tokenised securities rather than building it.
Flows confirm institutional re-engagement. A single-day net inflow of $999M into US spot bitcoin ETFs was the largest since October 2025. Balance-sheet players keep compounding. Bitmine bought 27,562 ETH and now holds over 4.9% of circulating supply against $17.1B in total investments. Strive added 1,355 BTC.
The more interesting capital event is collateral eligibility. Galaxy parked $100M in Sky's sUSDS and approved it as loan collateral. That is a genuine threshold for a DeFi savings token, because collateral recognition is what converts yield into balance-sheet utility.
Hashed is anchoring a $300M private credit fund using covenant-based underwriting, the first credible answer to the sector's financing bottleneck. Crypto.com's SEC registration for single-stock futures and planned US stock perpetuals is the most consequential commercial move, putting a retail-heavy venue into direct competition with CME and incumbent brokers. Marszalek's disclosure of joint SEC and CFTC engagement signals a negotiated path rather than a fight.
Where the Capital Is Not Going
Brazil's Resolution 561 is the real negative flow. Barring stablecoins from the FX settlement leg between licensed providers and overseas counterparties removes a genuine $1.1T-market use case from a major corridor starting 1 October, and it is enforceable. This pushes volume to less regulated corridors or into tokenised deposits.
Fairshake's $30M against Sherrod Brown is concentrated political capital, single-race, and the clearest priced bet on legislative outcomes in the set. OFAC's BitBank designation is a compliance cost rather than a market event, though it shows sanctions enforcement now targets crypto rails as critical infrastructure. Hormuz toll payments in Bitcoin are a sovereign-finance workaround being actively dismantled.
The Convergence
The three threads converge on a single mechanism: legal permission is being repriced as the scarce input, and the technology stack is being rebuilt around whoever holds it.
MoonPay buys the licence. The SEC grants the exemption. Brazil revokes the corridor. The ECB supplies the settlement leg. Solana supplies the throughput. Hut 8's $140M winning bid for Poolin's two Texas data centres supplies the physical layer, converting distressed bitcoin-mining capacity into AI hosting load and deepening ERCOT demand.
The pattern is vertical integration around regulated chokepoints. Firms are buying the right to intermediate rather than the technology to do so, because the technology is commoditising faster than the permission.
This is why the intelligence thread and the capital thread are the same story. Cheap frontier inference and 40 to 50% price cuts compress margins across the model layer, shifting value toward whoever controls cheap electrons, interconnect, and security telemetry. Simultaneously, capital flows toward licence stacks because those cannot be replicated by training runs. The scarce asset in both cases is a defensible position, not a capability.
The second-order effect is fragmentation. Rails are splitting into sanctioned and unsanctioned zones, with stablecoins caught in the middle. Ukraine gets defensive tooling while enterprises get breached silently. Brazil severs one corridor while the ECB builds another. The unified market that tokenisation promised is arriving as a set of jurisdictional islands, each with its own compliance perimeter.
What Could Break the Thesis
The thesis rests on permission being durable. Several things could undermine it.
- The SEC's innovation exemption lasts five years. If it is not renewed, the venue economics built on AMM-traded NMS stocks evaporate, and Solana's positioning as a live host becomes a stranded bet.
- ATS approval timing is uncertain. MoonPay's acquisition only pays off if North Capital's licences convert into operating volume on a predictable schedule.
- Stablecoin-rail concentration is a single point of failure. Binance's USDC deal, SoFi's Mastercard settlement, and Circle's position all depend on a small number of issuers and networks remaining in regulatory good standing.
- A capability glut could collide with regulatory disclosure costs. If frontier inference keeps deflating while disclosure liability rises, the labs funding the ecosystem face a margin squeeze that forces consolidation.
- Identity infrastructure remains unspecified. If KYC at the AMM layer is not solved, permissioned tokenised equities stall at the pilot stage regardless of the exemption.
The deepest risk is that permission is granted faster than the plumbing can absorb it. Cheaper inference accelerates agent proliferation faster than disclosure regimes, audit trails, or grid capacity can respond.
What to Watch Next
Three dated catalysts matter more than the rest.
The CFTC rulemaking's comment period is the clearest signal on US venue economics. Watch whether it formalises the exemption's logic or narrows it.
Crypto.com's approval timeline for single-stock futures determines whether a retail-heavy venue genuinely enters competition with CME, or whether the registration stalls.
Brazil's 1 October implementation date will show whether Resolution 561 pushes stablecoin volume into tokenised deposits and alternative corridors, or simply displaces it offshore.
Beyond the calendar, watch two structural indicators. First, whether collateral eligibility for DeFi savings tokens spreads beyond Galaxy's $100M sUSDS position, because that is the mechanism that converts yield into balance-sheet utility. Second, whether Hut 8 discloses its assumed power cost and funding route for the Poolin sites, because that determines dilution and tells you whether bitcoin-mining-to-AI conversion is a genuine trend or a distressed one-off.
The through-line to hold: own regulated-rail equity and collateral-eligible yield, not beta. The week rewarded permission, and the next one will show whether the plumbing can keep pace with it.